We are based on the local area and look at the worldHomepage - English
Hon Hai Group
Homepage
America
Mexico
Europe
Czech Republic
Slovakia
Press Center
Latest News
Hon Hai Technology Group (Foxconn) Announces  Third Quarter 2026 Financial Results
2026/11/12
Hon Hai Technology Group (Foxconn) Announces Third Quarter 2026 Financial Results
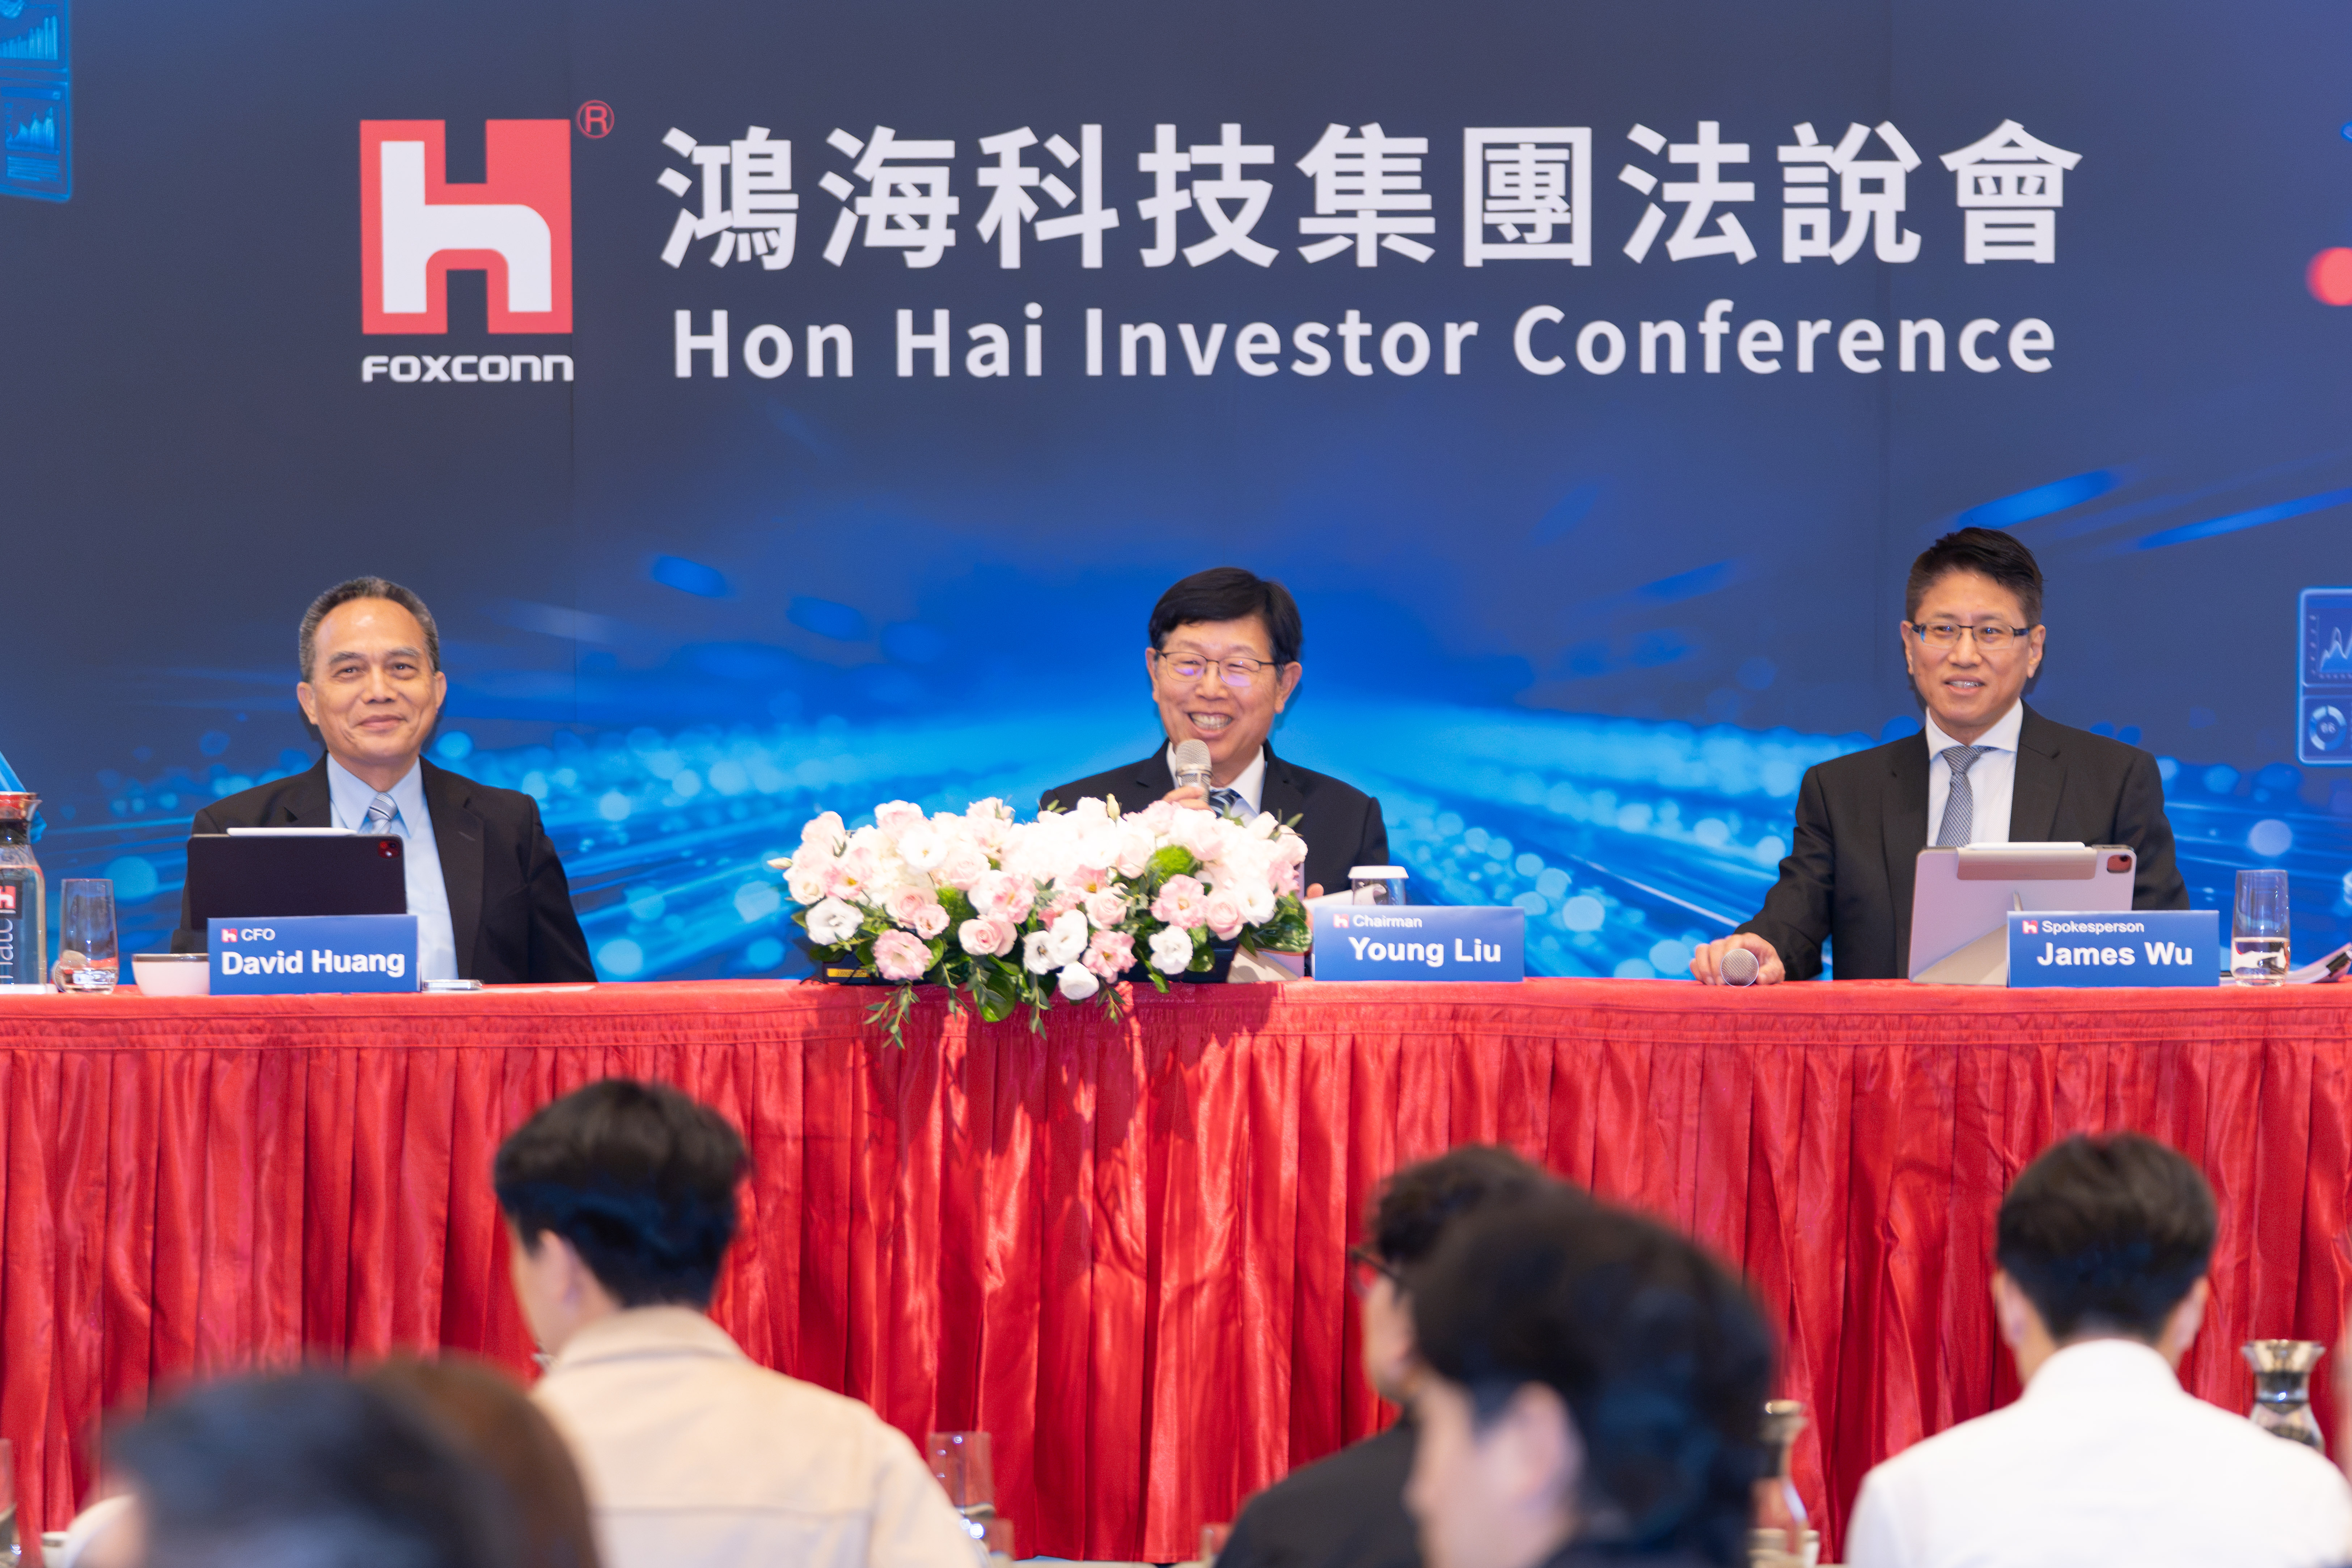
·      4Q26 demand strong, raising FY26 outlook for all 4 major product segments ·      Optimistic for 2027; net profit in 3Q26 sets new quarterly record ·      AI business yielding better profitability and capital efficiency ·      Key components demand surpassing supply is shared challenge for AI, ICT supply chains 12 November 2026, Taipei, Taiwan – Hon Hai Technology Group (Foxconn) (TWSE:2317) today announced its third quarter 2026 financial results. Revenue, gross profit, operating profit, and net profit for the third quarter and the first nine months of the year all reached record highs for the respective periods. Earnings per share (EPS) reached NT$5.51 for the July-September quarter and NT$13.35 for the January-September period – both representing sharply higher growth compared to same periods last year. Looking ahead to the fourth quarter, the company anticipates strong growth on both a quarterly and on-year basis. While the target for strong full-year growth remains unchanged, the outlook for all four major product segments has been revised upward. The company maintains a positive outlook for AI and smart consumer electronics products for the coming year and, for the first time, expressed an optimistic view regarding performance in 2027. In the third quarter, Foxconn recorded revenue of NT$3.02 trillion, up 46% on-year; gross profit of NT$181.5 billion jumped 39% at the same time; operating profit at NT$115.4 billion surged 64%; and net profit (attributable to owners of the parent company) of NT$77.5 billion, climbed 34% from a year ago. These figures also represent quarterly growth of 19%, 17%, 22%, and 29%, respectively, over the second quarter. EPS for the July-September period reached NT$5.51 – an increase of NT$1.36 from NT$4.15 in the same period a year ago, and up by NT$1.24 from the second quarter. Gross margin, operating margin, and net margin stood at 6.02%, 3.83%, and 2.57%, respectively. Net profit after tax also hit a new record for any quarter. For the January-September period, cumulative revenue reached NT$7.66 trillion, 39% higher on-year; with gross profit at NT$467 billion, up 35%; operating profit at NT$285.8 billion, rising 65%; and net profit (attributable to owners of the parent company) increasing 30% to NT$187.4 at the same time. Gross margin, operating margin, and net margin were 6.10%, 3.73%, and 2.45%, respectively, reflecting ongoing optimization of the company’s core operational profitability. EPS for the first three quarters of this year reached NT$13.35, an increase of NT$2.97 from the NT$10.38 recorded in the same period last year. The conference marked Foxconn’s return to an in-person quarterly investor meeting since the pandemic, with the option for online participation. Chairman Young Liu stated that in-person interaction provides investors with a deeper understanding of the company’s recent developments and future outlook. Going forward, Foxconn plans to hold hybrid (in-person + online) investor conferences annually around this time of year. Reflecting on the third quarter, the cloud and networking products segment – bolstered by robust demand for AI servers – exceeded even the most optimistic initial forecasts, serving as the primary driver behind the Group’s record-high revenue. Chairman Liu noted that AI servers have become Foxconn’s most significant growth engine and will continue to facilitate the optimization of both the company’s product mix and its client base. FY26 outlook raised for all 4 major product segments Looking ahead to the fourth quarter, Chairman Liu stated that the AI business is set to continue its growth. Combined with the arrival of the traditional peak season for ICT products, overall revenue is expected to show strong growth both sequentially and from year-ago levels. Specifically, with the shipment of a new generation of AI server racks, revenue from AI servers is projected to continue growing on a quarterly basis, while general-purpose servers are expected to see moderate growth. Together, these factors will drive significant on-quarter and strong on-year growth for the company’s cloud and networking products. The smart consumer electronics products segment is in its peak shipment period for the fourth quarter. With robust product demand and higher average selling prices, strong growth is anticipated both on a sequential and on-year basis. The computing products segment continues to be affected by tight memory supply, leading a likely slight decline quarter-over-quarter; however, rising prices for certain components have driven up average selling prices, pointing to significant year-over-year growth. Meanwhile, components and other products segment is expected to see significant quarter-over-quarter growth, supported by an increase in shipments related to core business operations. Regarding the full-year outlook, Chairman Liu indicated the target for strong growth remains unchanged. However, as operational visibility has improved since the investor conference in August, the company has raised its outlook across all four major product segments. Operational performance for the year has consistently exceeded initial expectations, a trend that is expected to continue into next year. Optimistic for 2027, focus on key component supply and external shifts Looking ahead to 2027, Chairman Liu stated that, based on current customer demand, he is confident in continued operational growth for the coming year. However, he noted that developments within the supply chain and the broader external environment warrant close attention. At present, tight supplies of chips, memory, and certain key components pose a shared challenge for the AI and consumer electronics supply chains. While the rollout of new production capacity will gradually alleviate these bottlenecks, overall demand is expected to continue exceeding supply next year, and tight market conditions may persist for some time. Furthermore, uncertainties in the global political and economic landscape – along with inflation, interest rates, and exchange rate fluctuations – can all impact operating costs, investment decisions, and supply chain configurations. Chairman Liu emphasized that in the face of such external shifts, robust corporate management capabilities become even more critical. He noted that the talent, capital, and supply chain management expertise that Foxconn has cultivated over the long term serve as a vital foundation for the Group’s positive outlook on future market prospects. AI growth is translating into returns As its AI business grows rapidly, Foxconn continues to use metrics such as Return on Equity (ROE), operating margin, and EBITDA to demonstrate the profitability and capital efficiency gains resulting from its operational expansion. Chairman Liu noted that during the period when product segments of smart consumer electronics and computing were the primary revenue drivers, the Group’s ROE generally remained below 10%; however, since cloud and networking products became the largest source of revenue last year, ROE has surpassed 11%. In the first three quarters of this year, the return on equity (ROE) reached 10.44% – a significant improvement over the same period last year – bringing the figure closer to the annual target of 12%. Chairman Liu noted that investments in the AI business are not only driving revenue growth, but are also yielding increasingly better profitability and capital efficiency. The Group has already begun discussions regarding a higher ROE target for the next phase, with the aim of consistently generating superior returns for shareholders. Regarding core business profitability, the growth in operating profit for the first three quarters of both 2024 and 2025 has consistently outpaced the growth in revenue and gross profit, with the gap continuing to widen. In the first three quarters of this year, operating profit increased by 65% year-on-year – a reflection of the Group’s ongoing improvements in vertical integration, automation, and operational efficiency. Coupled with the gradual realization of economies of scale, these factors have driven a strengthening of core profitability. Chairman Liu noted that, although the increase in unit selling prices has impacted profit margins, the operating profit margin for the first three quarters of this year still rose to 3.73% – a significant improvement over the 3.2% recorded for the full year last year, and a figure that also exceeds the 3% threshold set by the Group. Core business cash generation strengthening As investments in AI infrastructure continue to expand, Foxconn remains focused on the cash-generating capacity of its core business. The Group’s EBITDA for 2025 reached nearly NT$357 billion – more than double the figure recorded in 2020. In the first three quarters of this year, EBITDA has already surpassed the total for the entire previous year, reaching NT$369.2 billion – an increase of NT$123.6 billion, or 50.3% year-on-year – which outpaces the 43% growth in capital expenditures over the same period. Chairman Liu pointed out that the widening gap between EBITDA and the sum of capital expenditures and cash dividends, demonstrates that the cash-generating capacity driven by the growth of the AI business not only supports future capital expenditure requirements and higher cash dividends, but also further strengthens the company’s financial position, preserving the flexibility needed for future development. Regarding capital management, Foxconn adheres to the principle of "matching long-term funding with long-term investments, and short-term funding with short-term operational needs" – the latter being managed flexibly through borrowing and the optimization of the cash conversion cycle. With a debt-to-equity ratio of approximately 64%, the Group retains capacity to meet future capital requirements by issuing corporate bonds. Furthermore, it will employ flexible financing strategies – primarily through convertible bonds – to ensure a diverse mix of funding currencies while effectively managing the cost of capital. About Foxconn Hon Hai Technology Group (Foxconn) (TWSE:2317) is the world’s largest electronics manufacturer and leading technology solutions provider, ranking 23rd in Fortune Global 500. In 2025, revenue totaled TWD8.1 trillion (approx. USD260 billion). The Group’s market share in electronics manufacturing services (EMS) exceeds 40% and covers four major product segments: smart consumer electronics; cloud and networking; computing; and components and other. Operating over 240 campuses across 24 countries, Foxconn is one of the world’s largest employers with approx. 1 million employees during peak manufacturing season. We are committed to sustainability in the manufacturing process and serving as a best-practice model for global enterprises. The Group is guided by its 3+3+3 strategy, actively investing in industries of electric vehicles, digital health, and robotics; in technologies of artificial intelligence, semiconductors and next-generation communications; in intelligent platforms of Smart Manufacturing, Smart EV and Smart City. Foxconn is dedicated to becoming a comprehensive, world-class enterprise, with AI as its core driving force. Learn more at www.foxconn.com/en-us
2026/11/12
Hon Hai Technology Group (Foxconn) Announces  Second Quarter 2026 Financial Results
2026/08/12
Hon Hai Technology Group (Foxconn) Announces Second Quarter 2026 Financial Results
·      2Q26 revenue, operating profit, net profit all at record highs for same period ·      3Q26 to see strong YoY growth, significant QoQ growth ·      Solid gains in 3Q26 for cloud and networking & smart consumer electronics ·      2027 demand for AI production capacity to stay very strong ·      Capex to grow in US, including Texas, Wisconsin, Ohio, California ·      Electromobility new business gaining ground in New Zealand, Poland, Saudi Arabia--12 August 2026, Taipei, Taiwan – Hon Hai Technology Group (Foxconn) (TWSE:2317) today announced its second quarter 2026 financial results. Revenue in the April-June quarter reached NT$2.53 trillion, that alongside operating profit and net profit, all set new second-quarter records. Net profit for the quarter was NT$60 billion, and earnings per share reached NT$4.27. Looking ahead to the third quarter, the traditional peak season, operations are expected to gradually pick up. Overall, the July-September quarter is expected to see significant quarter-on-quarter growth and strong year-on-year growth. For the full year 2026, thanks to strong demand for AI servers and growth in smart consumer electronics, the outlook for strong growth remains unchanged. In the second quarter, revenue reached NT$2.53 trillion, up 41% on year; at the same time, gross profit was NT$154.5 billion, rising 36%; operating profit at NT$94.8 billion, increased 68%; and net profit (attributable to the parent company's owners) was NT$60 billion, gaining 35% on year. Gross profit margin, operating profit margin, and net profit margin were 6.12%, 3.75%, and 2.37%, respectively. EPS reached NT$4.27, an increase of NT$1.08 compared to NT$3.19 in the same period last year. Revenue, operating profit, and net profit all reached record highs for the same quarterly period. In the first half of 2026, revenue reached NT$4.65 trillion, increasing 35% from a year ago; at the same time, gross profit was NT$285.5 billion, up 33%; operating profit was NT$170.5 billion, jumping 65%; and net profit was NT$109.9 billion, rising 27%. Gross profit margin, operating profit margin, and net profit margin were 6.15%, 3.67%, and 2.37%, respectively. EPS reached NT$7.84, an increase of NT$1.61 compared to NT$6.23 in the same period last year. Revenue, operating profit, and net profit all reached record highs for the first half of the year. Amid significant market interest regarding the mass production progress of AI and smart consumer electronics products for key clients, Foxconn Rotating CEO Michael Chiang stated the Group is seeing sustained volume growth in AI server racks driven by continued capital expenditure expansion among cloud service providers (CSP). Cloud and networking products are projected for strong growth in the third quarter, with high double-digit increases both on-quarter and on-year. For the same period, revenue for smart consumer electronics, given traditional peak season in the second half of the year, is expected to show significant growth sequentially in the July-September quarter and compared to a year ago. As Foxconn continues to expand its market share in AI server racks, Chiang said Foxconn's advantage in AI lies in providing complete, end-to-end system solutions, rather than just single products. With Vera Rubin (VR) racks entering mass production in the third quarter, overall AI server rack revenue is expected to increase quarter-on-quarter, and shipments are projected to achieve high double-digit growth. For the full year this year, AI rack shipments are also expected to more than double. Shipments of high-performance networking products are moving ahead and full-year revenue from 800G and higher switches is expected to double, while co-packaged optics (CPO) all-optical switches are on track for mass production and shipment in the third quarter. Foxconn’s sustained strength in operational performance comes down to its global footprint and economies of scale, said Chiang. With more than 240 sites in 24 countries, and longstanding, deep development of vertically integrated and highly automated operations, alongside a high in-house production ratio of key components, the Group is able to maintain sound operating efficiency and yields in the face of high unit price and highly complex AI products. Taking an example, he said, currently the Group’s automation rates of processes in computer numerical control (CNC) and surface mount technology (SMT) are close to 100%. Ultimately, it is the collaboration with top-tier customers to develop products, focusing on forward-looking and proprietary technologies, increasing the proportion of high-value-added products, that drives Foxconn's transformation into a technology manufacturing platform service provider. On the subject of the Group’s cash flow supporting its huge operations and mass production work, Chiang said AI has brought significant benefits to Foxconn's financial performance. Investment expansion and order intake in the first half of this year has led to capital expenditure growing 5% on year to NT$80.9 billion, and net interest expense increasing by NT$6.6 billion annually. However, he pointed out that well-outpacing the spending and interest expense was a bigger 52% year-on-year jump in adjusted EBITDA in the first half, making clear a healthier cash flow. In the January-June period this year, adjusted EBITDA reached NT$227.7 billion, up by NT$77.6 billion. Regarding the ROE and operating profit margin indicators, Chiang stated the ROE for the first half of this year reached 6.21%, an increase of 0.73 percentage point compared to the same period last year, reaching half of the Group's 12% target, with further room for improvement. Operating profit margin – at 3.67% in the January-June period, improving 0.67 percentage point year-on-year – not only met the Group's 3% target, but should also exceed last year's full-year level of 3.2%. Looking ahead to next year, Chiang said customer demand for AI production capacity will still be very strong. Foxconn’s capex will continue to increase in locations including Taiwan, the United States, Mexico and Vietnam; among sites, in response to American localization needs, Texas, Wisconsin, Ohio and California will see build up in R&D and manufacturing capabilities. The Group currently has no plans for direct equity financing and will maintain a sound capital structure to meet future operational and expansion needs. Among positive developments in new business areas, Japan’s Mitsubishi Motors in New Zealand recently officially confirmed EV models under partnership, with Chiang noting vehicle deliveries starting in the second half of this year. In Europe, work with state-backed ElectroMobility Poland (EMP) is continuing to advance, while in MENA, production is expected to officially start in the fourth quarter for the joint venture in EV charging infrastructure in Saudi Arabia. Meanwhile, at home, delivery began in July for new car model CAVIRA based on the MODEL C, and the new Kaohsiung factory also started mass production of MODEL T and electric bus batteries. In a call out for October, Hon Hai Tech Day 2026 this year will be held October 30-31. In its 7th year, Foxconn’s flagship show will take place at an unprecedented scale, combining the first and fourth floors of Taipei Nangang Exhibition Center, Hall 1, to demonstrate the Group’s latest technological achievements from its three major smart platforms and deep integration of AI. New product reveals are planned. The two-day annual conference will launch for the first time a family-friendly pavilion for children to explore cool zones and dream jobs related to technology. Free entry on the second day, hands-on exploratory themes for the young include sustainability, mobility, smart factory and smart city. Foxconn sincerely invites one and all to come!     About Foxconn Hon Hai Technology Group (Foxconn) (TWSE:2317) is the world’s largest electronics manufacturer and leading technology solutions provider, ranking 23rd in Fortune Global 500. In 2025, revenue totaled TWD8.1 trillion (approx. USD260 billion). The Group’s market share in electronics manufacturing services (EMS) exceeds 40% and covers four major product segments: smart consumer electronics; cloud and networking; computing; and components and other. Operating over 240 campuses across 24 countries, Foxconn is one of the world’s largest employers with approx. 900,000 employees during peak manufacturing season. We are committed to sustainability in the manufacturing process and serving as a best-practice model for global enterprises. The Group is guided by its 3+3+3 strategy, actively investing in industries of electric vehicles, digital health, and robotics; in technologies of artificial intelligence, semiconductors and next-generation communications; in intelligent platforms of Smart Manufacturing, Smart EV and Smart City. Foxconn is dedicated to becoming a comprehensive, world-class enterprise, with AI as its core driving force. Learn more at www.foxconn.com/en-us
2026/08/12
Hon Hai Technology Group (Foxconn) Announces  First Quarter 2026 Financial Results
2026/05/14
Hon Hai Technology Group (Foxconn) Announces First Quarter 2026 Financial Results
• 1Q26 net profit up 19% on-year, operating profit surges 63% on-year• 1Q26 gross margin and operating profit margin both improve on-year• AI demand driving significant QoQ, strong YoY growth for 2Q26• FY 2026 outlook for strong growth unchanged14 May 2026, Taipei, Taiwan – Hon Hai Technology Group (Foxconn) (TWSE:2317) today announced its first quarter 2026 financial results:Revenue reached a record high of NT$2.12 trillion in the January-March period, while net profit attributable to the parent company totaled NT$49.9 billion, increasing NT$7.8 billion or 19% from the same period a year ago. Earnings per share in the first quarter hit NT$3.56. Looking ahead to the second quarter, although it is traditionally a slow season for the ICT industry, the Group expects to maintain an uptrend due to strong AI demand, with significant quarter-on-quarter growth and strong year-on-year growth. The full-year outlook remains unchanged, maintaining strong growth and providing greater visibility.In the first quarter of 2026, revenue reached NT$2.12 trillion, a year-on-year increase of 29%; gross profit was NT$131 billion, up 30%; operating profit was NT$75.6 billion, surging 63%; and net profit (attributable to the parent company's owners) was NT$49.9 billion, rising 19%. The gross profit margin, operating profit margin, and net profit margin were 6.18%, 3.57%, and 2.36%, respectively, compared with 6.11%, 2.83%, and 2.56% in the same period last year, showing an increase in both gross profit margin and operating profit margin. EPS reached NT$3.56, an increase of NT$0.53 compared with NT$3.03 in the same period last year.Faced with sustained, strong demand for the Group’s AI business, Foxconn Rotating CEO Michael Chiang said that with the ICT industry entering the traditional off-season in the first quarter, coupled with rapid growth in AI server demand, the Cloud and Networking product segment now accounts for nearly 50% of revenue. This demonstrates that the Group’s AI strategy has already brought about a structural transformation, helping to mitigate the seasonality of the ICT industry. At the same time, with a more diversified AI customer base, the Group’s product portfolio has become more balanced.Looking ahead to the Group’s second quarter performance, although the quarter is traditionally a slow season for the ICT industry, expectations are for maintaining an uptrend, with significant growth quarter-on-quarter and strong growth year-on-year, thanks to strong AI demand. The full-year outlook for strong growth remains unchanged. Visibility is higher.The Group's main product segments are Cloud and Networking, and Smart Consumer Electronics. In terms of the former, strong growth is expected both on a quarterly and yearly basis. In terms of the latter, with overall demand better than last year, significant growth is expected.During the investor call, the Group shared how it is building a moat through a sound financial constitution, while at the same time expanding investment and spending. Last year, capital expenditures increased about 27% on-year to NT$174 billion, and should rise more than 30% this year. The investments are primarily focused on regional manufacturing deployment, automation implementation, and upgrade of core capacity.Taking the first quarter as an example, the Group’s EBITDA rose to NT$102.4 billion. This indicates that as the Group actively invests in future growth, its overall financial health is staying robust. Capex is gradually translating into revenue and profit growth ahead.In addition, in terms of enhancing corporate value, the Group’s ROE for the first quarter reached 2.88%, representing a clear improvement compared to the same period over the past two years. This reflects ongoing progress in optimizing the Group’s profitability structure and operational efficiency. As AI-related business grows, as well as benefits materialize from a global footprint and vertical integration, there is further upside potential for ROE.Regarding recent market focus on co-packaged optics (CPO), rotating CEO Chiang said that CPO switches are scheduled to enter mass production in the third quarter, with annual shipments expected to reach tens of thousands of units. Based on current visibility, shipments are projected to grow multi-fold next year.CPO and 1.6T high-end switch products are currently being developed and prepared for mass production in cooperation with major cloud and AI data center customers, with shipments expected to begin in the third quarter. In addition to switch design and assembly, the Group continues to strengthen its capabilities in key components such as optical modules, optoelectronic integration, cables, connectors, high-speed transmission, and power management. By increasing the proportion of in-house production and integration, the Group aims to further enhance system performance, delivery efficiency, and supply chain control.For AI rack shipments, the Group expects to keep high double-digit growth in the second quarter. For the full year, AI rack shipments are projected to more than double, with quarterly volumes increasing sequentially as customer projects progress. In the area of high-speed switches above 800G, driven by growing demand for high-speed networking architectures in AI data centers, related product shipments and revenue this year also have the potential to double.In robotics, one of the key areas in the Group’s “3+3+3” strategy, humanoid robots and collaborative robots have already been introduced in US manufacturing sites in the second quarter. Operational data will be collected to support subsequent model optimization and large-scale deployment. In Smart City, the Group continues to deepen collaboration with local governments and partners, while promoting the export of integrated solutions, aiming to replicate successful experiences across more countries and cities.Lastly, in next-generation communications, the second-generation “PEARL” – Foxconn’s low Earth orbit (LEO) satellites – successfully launched on May 3 aboard a SpaceX Falcon 9 rocket, entering their designated orbit.While the first-generation satellites focused on satellite-to-ground communication experiments and system validation, the latest in orbit are equipped with Ka-band inter-satellite link (ISL) payloads. The two satellites will not only enable broadband communication between satellites and ground stations, but also validate inter-satellite communication between each other.Following the successful launch of the second-generation satellites, the Group will continue to accelerate its expansion in the space sector, focusing on diverse application scenarios such as mobile communication supplements, direct-to-device satellite connectivity, and connectivity in remote areas, further expanding opportunities in LEO satellite technology and smart communications integration.
2026/05/14